

Blogs
Global Synthetic Leathers Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The global synthetic leathers market generated approximately $35,000 million in revenue in 2020 and is projected to reach $68,000 million by 2035, reflecting a robust compound annual growth rate. Consistent demand from automotive, footwear, fashion, and furnishing sectors is driving expansion, with significant uptake in Asia-Pacific due to manufacturing capacity and cost efficiency. The market saw a sharp rebound post-pandemic, with growth accelerating from 2023 onward as sustainability initiatives gained traction and new innovations entered the market. Revenue growth is anticipated to remain steady, underpinned by technological advancements, bio-based alternatives, and rising demand in emerging economies.
Read More - https://bussinessinsights.com/research-report/global-synthetic-leathers
Footwear continues to be the largest application segment for synthetic leather globally, accounting for 38% of total market share in 2025. The automotive sector has surged to 25%, spurred by auto OEMs and consumer preference for low-maintenance, stylish interiors. Furnishing (18%) remains important for both residential and commercial uses, benefiting from synthetic leather’s endurance and design appeal. Clothing, bags & wallets, and sports cumulatively represent approximately 19%, with demand rising in urban and athleisure markets. Electronics and other specialty applications are emerging but remain niche. The applications landscape is evolving as consumers and industries prioritize sustainability, performance, and design, reshaping where synthetic leathers find their biggest uses.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-synthetic-leathers
Frequently Asked Questions
Who are the key players in Global Synthetic Leathers industry?
Top players include Kuraray Co., Ltd., Teijin Limited, Toray Industries, Inc., Fujian Polyrech Technology Co., Ltd., and Mayur Uniquoters Ltd. These companies lead the market with innovations in eco-friendly synthetic leather, wide global distribution, and strategic partnerships, catering to automotive, footwear, and fashion segments.
What is the Global Synthetic Leathers growth?
The Global Synthetic Leather market is witnessing robust growth, driven by increasing demand for animal-free leather and sustainability trends. For example, in 2023, Toray Industries reported significant revenue growth in its man-made leather segment, propelled by rising applications in automotive and luxury goods.
Which segment accounted for the largest Global Synthetic Leathers share?
The footwear segment accounted for the largest share in the global synthetic leather market. High consumption in the production of shoes and sneakers, especially by leading brands like Adidas and Nike, due to affordability, durability, and vegan trends, has significantly boosted demand for synthetic leathers in this application.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Desktop IP Phone Market Hits $385M in 2025, Projected 4.25% CAGR to 2032
By PW Consulting, 2026-09-07
Desktop IP Phone Market 2026: A Strategic Roadmap for Enterprise Communications Buyers
The enterprise communications landscape is undergoing a quiet but profound recalibration. As organizations navigate hybrid work mandates, cloud migration backlogs, and tightening security postures, the humble desktop IP phone has reemerged not as a legacy relic but as a strategically placed endpoint that bridges unified communications, physical workspace design, and operational resilience. For executives, procurement leaders, and IT architects, the decisions made in 2026 around desktop IP telephony will echo across operational budgets, compliance postures, and employee experience metrics for years to come. Our newly published Desktop IP Phone Market research study is designed precisely for that moment of decision-making. Rather than offering a superficial snapshot, the report delivers a structured, forward-looking intelligence framework that helps leadership teams separate transient vendor narratives from structural market shifts.
Europium Acetate Market
The strategic value of this study lies in its ability to translate complex market trajectories into actionable procurement, deployment, and partnership choices. Base-year data anchored in 2025 reflects a market that has already absorbed years of infrastructure modernization, while the forecast window stretching from 2026 to 2032 captures the next wave of adoption curves, technology refinements, and competitive repositioning. Total market revenue, measured in millions of USD, moved from approximately 301.48 in 2020 to 385.02 in 2025, signaling a sustained climb that outpaces many adjacent endpoint categories. The projected trajectory through 2032 points toward continued expansion, with the 2026 forecast reading 409.53 and the 2032 horizon reaching 517.92. These figures are not merely arithmetic; they represent cumulative capital allocation, refresh-cycle timing, and competitive intensity across regions and verticals.
Worldwide Screw and Barrel Market
Crucially, the study captures a forecast period CAGR of 4.25 percent, a rate that reflects deliberate, enterprise-led growth rather than speculative hype. That percentage matters to decision-makers because it frames expectations for budget planning, inventory forecasting, and vendor negotiation leverage. A mid-single-digit growth environment rewards disciplined total cost of ownership modeling and penalizes reactive purchasing. The historical runway from 2020 through 2025 demonstrates how the market absorbed pandemic-era demand shocks, supply constraints, and accelerated digital transformation, while the forward window highlights where growth compounds through product innovation, integration depth, and regional maturation rather than through one-off order spikes.
Hoof Care Spray Market
Why 2026 Is a Pivotal Year for Desktop IP Phone Strategy
The 2026 decision environment is shaped by a convergence of forces that make endpoint selection more consequential than in prior refresh cycles. On the regulatory front, compliance and procurement scrutiny are intensifying. Recent developments have placed new constraints on the authorization and sale of certain equipment categories, and expanded covered-list rules effective in March 2026 have added complexity to sourcing decisions for IT teams that must now weigh supply continuity against geopolitical and regulatory exposure. Complementing these shifts, broader telecommunications equipment restrictions—including the placement of select vendors' devices on covered lists—have prompted enterprises to reassess vendor consolidation strategies and to prioritize interoperability, firmware lifecycle commitments, and transparent sourcing models.
Supply chain realities further sharpen the focus on endpoint strategy. Component shortages and disruptions affecting specialized electronic parts continue to extend lead times and elevate costs, which means that procurement timelines, inventory buffers, and vendor delivery reliability are now first-order planning variables rather than secondary considerations. For enterprises evaluating desktop IP phones in 2026, these dynamics elevate the importance of product roadmaps that emphasize longevity, modular firmware support, and ecosystem compatibility. The organizations that will navigate this period most effectively are those treating desktop IP phones as integrated components of a broader communications architecture—one where voice, video, presence, security, and network policy converge.
Against this backdrop, the desktop IP phone is no longer a commoditized accessory. It is an endpoint that must demonstrate compatibility with unified communications platforms, support enterprise-grade security expectations, and deliver a user experience that justifies physical deployment even in environments where soft clients and mobile devices are prevalent. The market research study examines these pressures through the lens of real procurement and deployment scenarios, ensuring that the analysis remains grounded in operational reality rather than abstract technology trends.
What the Research Delivers: An Operational Intelligence Framework
The Desktop IP Phone Market study is structured to support multi-stakeholder decision-making. It moves beyond top-line sizing to provide the analytical scaffolding necessary for segmentation, competitive benchmarking, and scenario planning. The report covers a detailed segmentation architecture that disentangles how market value is distributed across type, application, and geography without reducing the analysis to static snapshots. By examining the Video Desktop IP Phone category alongside Common Desktop IP Phone and other product variants, the study illuminates how form factor, display capability, and feature packaging influence buying behavior across different organizational contexts. Rather than treating all desktop endpoints as interchangeable, the segmentation analysis maps functional differentiation to procurement intent, helping teams align product selection with use-case requirements such as executive conferencing, frontline office deployment, or specialized departmental workflows.
The application-side segmentation further clarifies where demand is concentrated and why. Enterprise deployments continue to anchor the market's core, reflecting the centrality of desk-based voice and video endpoints in structured organizational environments. Office-centric demand and other application segments add nuance to rollout planning, particularly for organizations managing mixed environments that span corporate headquarters, satellite locations, and shared operational spaces. By situating these application patterns within the broader market trajectory, the report enables planners to prioritize deployment sequencing, lifecycle refresh timing, and support-model design with greater precision.
Geographic analysis is presented with the same analytical discipline. The report examines regional market structures across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing context on how regional maturity, regulatory environments, procurement norms, and deployment densities shape demand. Rather than isolating regions as disconnected markets, the study frames them as interconnected nodes within global enterprise strategies, where vendor presence, channel depth, and localization requirements influence both purchasing decisions and total cost of ownership. This regional framing is especially valuable for multinational organizations coordinating standardized endpoint policies while accommodating local compliance, language, and infrastructure realities.
Beyond segmentation, the research incorporates a rigorous competitive landscape assessment. It profiles the organizations that define product direction, set interoperability expectations, and shape procurement negotiations across the market. Cisco Systems maintains a prominent position through its 8800 Series and 6800/7800 series desk phones, which support full-featured VoIP with HD voice, video, and MPP firmware—an ecosystem-aligned approach that resonates with enterprises already invested in broader Cisco communications and networking architectures. Yealink, operating from Suzhou, Jiangsu, has built a strong desktop presence through its T-Series and W-Series desktop IP phones, which integrate Wi-Fi, Bluetooth, and support for up to 16 lines, positioning the brand as a flexible option for enterprise VoIP systems that demand mobility features and multi-line handling. Poly, now part of HP Inc., offers the VVX and Edge Series desk phones with color displays, support for up to 32 lines, and NoiseBlockAI technology, emphasizing audio clarity and high-density line management in professional environments.
The competitive field extends well beyond these headline names. Mitel Networks contributes the 6900 Series desktop IP phones, which combine Wi-Fi and Bluetooth support with PCLink for PC collaboration, appealing to organizations that value tighter integration between endpoints and desktop productivity workflows. Grandstream Networks, based in Belmont, Massachusetts, advances the GRP-Series of wired and Wi-Fi desktop IP phones designed around open SIP standards and enterprise integration, a posture that attracts deployments seeking interoperability and flexible system design. Fanvil focuses on professional IP desktop phones with rich functionality and high-quality builds for enterprise use, reinforcing the value proposition of durability and feature depth in demanding office environments. snom's UC Edition desktop IP phones, with Microsoft Lync and Teams qualification, address organizations that prioritize platform certification and unified communications compatibility as procurement prerequisites. Gigaset rounds out the competitive picture with a professional IP desktop phone portfolio developed for European markets, reflecting the importance of regional product strategy and localized go-to-market execution.
This competitive analysis is not a static company directory. It is constructed to reveal how product portfolios, firmware strategies, platform certifications, and regional focus intersect with procurement priorities. The study also incorporates recent market movements that illustrate how vendors are actively reshaping their positions. Gigaset expanded its professional category with a new IP desktop phone portfolio of three models and launched availability across all European markets in 2025, a sequence that signals deliberate regional emphasis and portfolio refinement. In parallel, snom's 370 UC Edition Desktop IP Phone achieved Microsoft Lync qualification in 2025, a milestone that underscores the persistent importance of platform certification in enterprise buying criteria. These developments are interpreted within the report as indicators of competitive momentum, product-directional shifts, and the evolving expectations placed on desktop IP endpoints.
Market Concentration and the Strategic Implications of an Oligopolistic Structure
One of the study's most decision-relevant contributions is its analysis of market concentration. The market exhibits a CR3 of 63.1 percent and a CR5 of 73.4 percent, indicating that a relatively small group of leading vendors commands a substantial share of revenue. For enterprise buyers, this concentration carries both benefits and risks. On one side, it suggests mature product portfolios, established interoperability ecosystems, and predictable support frameworks from the largest players. On the other side, it raises questions about pricing leverage, vendor lock-in, and the resilience of supply and firmware roadmaps if competitive intensity shifts.
The report contextualizes concentration not as a reason to default to incumbents, but as a parameter for disciplined evaluation. Enterprises are encouraged to weigh ecosystem alignment against openness, platform certification against long-term flexibility, and brand presence against total cost of ownership across multiple refresh cycles. In a concentrated market, negotiation strategy, lifecycle planning, and integration requirements become the true differentiators of procurement success. The research provides the comparative structure needed to evaluate those trade-offs systematically rather than reactively.
Translating Market Data Into Procurement and Deployment Decisions
The practical value of the study lies in its ability to connect macro trajectory with operational execution. When decision-makers understand how the market has grown from 2020 through 2025 and how the forecast extends toward 2032, they can better judge whether current procurement timing aligns with broader adoption momentum or risks buying into a slowing segment. When they examine how video-centric desktop IP offerings compare with common desktop variants, they can align hardware selection with actual usage patterns instead of defaulting to uniform endpoint standardization. When they assess application-side demand structures, they can sequence deployments to prioritize high-impact environments while managing budget phasing more effectively.
The study also supports vendor evaluation beyond feature lists. By mapping product characteristics to enterprise requirements such as HD voice quality, video readiness, multi-line capacity, wireless integration, noise suppression, platform certification, and open SIP compatibility, the report helps procurement teams build scoring frameworks that reflect operational priorities. This is particularly important in 2026, when regulatory and supply chain pressures make vendor selection a multi-dimensional exercise. A phone that satisfies a feature checklist may still underdeliver if firmware support timelines, regional availability, or certification status do not align with enterprise deployment schedules. The research's competitive and segmentation analyses are designed to expose those dependencies before purchase commitments are made.
How to Use This Study Within Your 2026 Planning Cycle
The Desktop IP Phone Market research is built to integrate with existing planning processes rather than interrupt them. It can inform budget forecasting by anchoring expectations in observed historical progression and forecast-period momentum. It can support vendor shortlisting by providing a structured basis for comparing portfolio breadth, platform alignment, and regional execution. It can guide rollout planning by showing how application and regional patterns interact with deployment density and support-model design. It can also strengthen negotiation positions by situating procurement decisions within a market where concentration, product differentiation, and regulatory dynamics all influence value creation.
For organizations managingmixed endpoint environments, the report's segmentation detail helps clarify where standardization adds value and where context-specific selection is warranted. For multinational teams, the regional framing supports coordination between global policy and local execution. For IT and procurement leaders managing risk, the regulatory and supply chain context embedded in the analysis reinforces the importance of sourcing discipline and lifecycle planning. In each case, the study is intended to reduce uncertainty without oversimplifying the decision space.
A Clear View of Where the Market Is Heading
The Desktop IP Phone Market will continue to be shaped by the interplay of enterprise adoption discipline, product differentiation, platform integration, and external pressures from regulation and supply chain conditions. The upward revenue trajectory reflected in the 2026 forecast and extending into 2032 indicates that demand is not collapsing into mobility-only paradigms; instead, it is being redefined around endpoints that deliver reliability, integration, and user experience in environments where voice and video remain mission-critical. At the same time, the mid-single-digit CAGR reminds planners that growth is methodical, which means timing, selection, and negotiation strategy matter as much as the technology itself.
This research study is designed to give decision-makers a credible, structured view of that reality. It offers the historical context to understand where the market has been, the segmentation depth to understand how value is distributed, the competitive analysis to understand who is shaping the landscape, and the forward-looking framework to anticipate where procurement conditions are heading. By combining these elements into a single intelligence asset, the report helps enterprises move from reactive endpoint purchasing to strategic communications infrastructure planning.
The full study contains the detailed data sets, segmentation splits, competitive profiles, and recent-market developments that support rigorous internal review and external negotiation. To access the complete analysis and the underlying intelligence that informs these strategic observations, visit the source page for the Desktop IP Phone Market research. There, you will find the full segmentation framework, company assessments, and market-trajectory detail needed to turn 2026 uncertainty into a defensible, data-informed action plan.
For detailed analysis of this topic, please visit the official page: Desktop IP Phone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Construction Chemicals Market to Hit $101.5B by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Intelligence for the Construction Chemicals Market (2026-2032)
The global construction chemicals industry stands at a critical inflection point. As infrastructure aging, urbanization trends, and sustainability mandates converge, the sector is transitioning from a commoditized materials space into a technology-driven, performance-oriented ecosystem. For executives, investors, and strategic planners operating in 2026, understanding this transition is no longer optional. It is a prerequisite for capital allocation, portfolio positioning, and competitive resilience.
Worldwide Automatic Transport Robot Market
This market research report delivers a comprehensive, data-anchored blueprint of the construction chemicals landscape, covering historical performance from 2020 through 2025 and extending forward-looking projections across the 2026-2032 forecast horizon. The analysis is designed to cut through market noise, quantify structural drivers, and map the competitive architecture that will define industry winners in the coming years.
Worldwide Building ETFE (ethylene-tetrafluoroethylene copolymer) Membrane Market
Executive Market Trajectory and Structural Growth Context
The industry has demonstrated consistent expansion over the past half-decade, supported by steady construction activity, regulatory upgrades in building performance, and incremental adoption of advanced chemical formulations. Historical revenue progression from 2020 to 2025 reflects a sector that has navigated supply chain volatility, raw material price fluctuations, and shifting project pipelines while maintaining a clear upward trajectory. Building on this foundation, the forecast period is projected to sustain a compound annual growth rate of 6.5 percent, with market valuation advancing toward the 100 billion dollar threshold by the close of the forecast window.
Worldwide Rad-hard Semiconductor Market
This growth profile is not uniform across time or geography. The acceleration curve reflects the interplay of infrastructure stimulus programs, commercial and residential construction cycles, and the increasing specification of high-performance chemical solutions that extend asset life, reduce maintenance burdens, and improve structural reliability. For decision-makers, the strategic implication is clear: the market is large enough to absorb new entrants and product innovations, yet fragmented and regionally nuanced enough that generic strategies will underperform without localized execution and technical differentiation.
The report quantifies these macro trends while deliberately reserving granular regional and application-level breakdowns for the full dataset. This allows leadership teams to validate directional assumptions before diving into the specific splits that will inform country-level entry plans, channel strategies, and segment prioritization.
Industry Dynamics: Raw Material Pressures, Regulatory Shifts, and the Sustainability Imperative
The operating environment for construction chemical manufacturers and suppliers is being reshaped by simultaneous pressures on the cost side and the compliance side. Raw material dynamics have become a recurring strategic variable rather than an occasional disruption. In early 2026, pricing for MDI products in North America moved upward by 22 to 35 cents per pound, driven by supply constraints and broader raw material shortages. At the same time, dimethyldichlorosilane prices climbed 28 percent year-on-year in the first quarter of 2026, reflecting outages at Chinese chlor-alkali units and elevated tariffs on silicon metal. In Northeast Asia, upstream benzene and ethylene costs contributed to a 15.3 percent upward movement in styrene pricing during the same period.
These input cost movements matter because construction chemicals sit at the intersection of petrochemical feedstocks, specialty intermediates, and performance additives. Margin structures are sensitive to feedstock volatility, and procurement agility is increasingly a competitive differentiator. The report examines how leading players are responding through formulation optimization, supplier diversification, inventory strategies, and selective pass-through mechanisms, without exposing the proprietary margin models and cost-ecosystem assessments contained in the full analysis.
On the regulatory front, the landscape is tightening in ways that directly affect product development, testing, and market access. The new Construction Products Regulation in the European Union has entered into force, imposing stricter compliance requirements for construction chemical products. This shift raises the bar for documentation, performance verification, and lifecycle transparency. For multinational suppliers, the EU framework often becomes a de facto benchmark that influences product design and regulatory strategies in other regions as well.
Layering onto compliance is the accelerating emphasis on sustainability. Manufacturers are expanding eco-friendly waterproofing solutions and low-impact formulations to align with green building certifications, public procurement requirements, and customer expectations around embodied carbon and environmental footprint. The industry is moving beyond marketing claims toward measurable performance attributes, which means that R&D roadmaps, patent positioning, and product certification pipelines are becoming strategic assets in their own right.
The report integrates these dynamics into a cohesive market forces framework, helping readers distinguish between transient price shocks and structural cost shifts, and between regulatory compliance burdens and competitive opportunities created by early movers in sustainable product portfolios.
Competitive Architecture: Consolidation, Capability Build-Out, and Regional Re-positioning
The construction chemicals sector is characterized by a concentrated tier of global specialists operating alongside strong regional players and niche technology providers. The report profiles the core companies that are shaping competitive outcomes, including Sika AG, BASF SE through its Master Builders Solutions brand, MAPEI S.p.A., Dow Inc., Saint-Gobain, Arkema S.A., RPM International Inc., GCP Applied Technologies, Fosroc International, Pidilite Industries Limited, Wacker Chemie AG, Nouryon Holding B.V., and Chryso Group.
Rather than treating these firms as static corporate listings, the analysis maps their strategic positioning across concrete admixtures, waterproofing and roofing systems, flooring chemicals, sealants and adhesives, and repair and restoration solutions. The focus is on where each organization is building capability, where it is exposed to input cost risk, and how it is leveraging distribution networks, technical service teams, and application expertise to defend or expand share.
Recent corporate activity underscores a clear consolidation and capability-acquisition rhythm. In 2025, Saint-Gobain acquired the business assets of Interstar Materials, Inc., strengthening its Construction Chemicals activities in the United States and Canada. That move was followed by the completion of Saint-Gobain's acquisition of Fosroc, a leading player in construction chemicals across Asia and emerging markets, consolidating a broader international footprint and expanding access to high-growth regions. In parallel, Master Builders Solutions expanded its U.S. manufacturing footprint with two new admixture sites, signaling a commitment to capacity and proximity to key customer segments. Master Builders Solutions also inaugurated a new state-of-the-art manufacturing facility in Taloja, Navi Mumbai, India, reinforcing its presence in a market where infrastructure demand and urbanization continue to drive volume growth.
Trade presence and solution integration are equally indicative of strategic intent. Saint-Gobain showcased its unified construction chemicals solutions at World of Concrete 2026, highlighting the industry's broader move toward bundled performance offerings rather than isolated product sales. These developments matter because they reveal how incumbents are preparing for the next cycle: through capacity investment in priority markets, acquisition of specialized portfolios, and stronger integration across admixture, waterproofing, and repair ecosystems.
The report translates these moves into a competitive intensity assessment, including concentration patterns that illustrate how value is distributed across the top players. The top three firms collectively account for 52 percent of market revenue, while the top five reach 61 percent. This concentration profile signals that scale, technical portfolio breadth, and global service infrastructure remain powerful advantages, but it also leaves meaningful room for specialized challengers, regional leaders, and innovation-led entrants in adjacent segments. The full analysis provides a more detailed mapping of share dynamics and strategic group behavior, while preserving the granular splits for the complete report.
Product and Application Architecture: Where Value Is Created and Captured
Construction chemicals are no longer a supporting category. They are increasingly central to specification decisions because they influence durability, speed of construction, lifecycle cost, and overall building performance. The product landscape analyzed in the report spans concrete admixtures, waterproofing and roofing systems, flooring chemicals, sealants and adhesives, and a set of specialized repair and restoration solutions. Each category carries distinct demand drivers, formulation complexity, and margin characteristics, and each responds differently to regional construction practices and project types.
Concrete admixtures remain a cornerstone of the sector because they directly affect workability, strength development, durability, and construction efficiency. As projects demand faster cycle times, more resilient structures, and lower water-cement ratios in certain applications, admixture technology continues to evolve. Waterproofing and roofing solutions are gaining strategic importance as asset owners prioritize moisture management, energy efficiency, and long-term protection against environmental exposure. Flooring chemicals serve both aesthetic and functional requirements in commercial, industrial, and residential settings, while sealants and adhesives underpin envelope integrity, joint performance, and assembly reliability across multiple construction systems. Repair and restoration chemicals address the growing need to extend the service life of existing assets, a theme that becomes more prominent as infrastructure ages and renovation activity increases.
On the application side, demand is distributed across residential, non-residential, infrastructure, and repair segments. The balance among these segments varies by region, economic cycle, and public investment pipeline. Residential construction tends to be more cyclical and sensitive to housing market conditions, while non-residential projects reflect commercial development, institutional spending, and workplace transformation trends. Infrastructure demand is shaped by public capital programs, transit expansion, utilities modernization, and resilience-focused rebuilds. Repair and maintenance applications represent a smaller but strategically important pool, often linked to lifecycle management and the macroeconomic value of asset preservation.
The report structures these product and application dimensions around their strategic implications: where formulation leadership creates pricing power, where service and technical support influence specification, and where regional construction norms shape adoption curves. This framing allows readers to identify the segments most aligned with their capabilities before accessing the detailed breakdowns that support precise segment planning.
What the Report Delivers: Commercial Intelligence for 2026 Decision-Making
This market research is built for execution, not just observation. It is intended to support strategic planning, investment prioritization, competitive positioning, and market-entry evaluation in a sector where technical credibility and regional execution often determine outcomes more than broad market narratives.
The report includes the following operational content:
- Historical market sizing from 2020 to 2025, establishing a verified baseline for growth analysis and scenario calibration
- Forecast projections from 2026 to 2032, anchored to the 6.5 percent CAGR trajectory and extending to the projected 2032 valuation threshold
- Segment-level evaluation across product types and application categories, with guidance on where demand is structurally strengthening and where competitive intensity is rising
- Regional demand context that distinguishes between mature, stable markets and faster-growing regions without prematurely disclosing the full regional splits
- Competitive profiling of leading global and regional players, including capabilities, strategic moves, and positioning across core product families
- Recent corporate developments such as capacity expansions, acquisitions, facility inaugurations, and trade-show integrations that signal forward strategy
- Input cost and regulatory dynamics, including MDI pricing movements, silane and styrene cost pressures, and the impact of the new EU Construction Products Regulation
- Sustainability and compliance themes that affect product development, certification, and customer specification behavior
- Strategic implications for manufacturers, distributors, specifiers, and investors seeking to align portfolio choices with market reality
By combining macro growth context with company-level activity and sector-specific cost and regulatory signals, the report creates a decision-ready environment. Readers can test assumptions about demand durability, assess exposure to feedstock volatility, anticipate compliance-driven product changes, and evaluate where consolidation or capability investment is likely to reshape competitive access.
How to Use This Intelligence in 2026
For senior leadership teams, the immediate value of this research lies in its ability to convert a complex market into an actionable strategic map. The 2026 decision environment is shaped by three overlapping questions: where growth is most durable, where cost and compliance pressures will reshape economics, and where competitive positioning will be won through technology, service, or scale.
The report helps answer these questions by separating long-term structural demand from short-term project cyclicality, by clarifying which product families are most exposed to input cost volatility, and by highlighting the corporate moves that indicate where incumbents are placing their bets. It also provides a basis for scenario planning, whether the objective is to evaluate new geographic entry, prioritize R&D investment, refine channel strategy, or assess acquisition targets and partnership opportunities.
Because the construction chemicals market rewards specificity, the report intentionally preserves detailed regional and application-level data for the full edition. This ensures that decision-makers can first align on direction and strategic logic, then access the precise figures needed for country-level planning, segment targeting, and commercial modeling.
Strategic Conclusion: Positioning for the 2026-2032 Cycle
The construction chemicals market is entering a phase in which growth, regulation, sustainability, and consolidation will interact more intensely than in previous cycles. Historical momentum from 2020 to 2025 has set a solid foundation, and the forecast trajectory through 2032 points to continued expansion at a meaningful pace. Yet the operational reality for companies is more nuanced: input cost swings, evolving compliance requirements, regional demand differences, and concentrated competition all demand a disciplined strategic Response.
This report is designed to give executives that discipline. It combines validated market sizing, forward-looking growth analysis, competitive profiling, and recent industry developments into a single integrated view. It also respects the complexity of the sector by keeping the most granular splits and proprietary breakdowns within the full research package, where they can be used for detailed planning without diluting the strategic narrative.
For organizations seeking to act with confidence in 2026, the next step is to translate this market-level perspective into segment-specific strategy. The complete report provides the deeper data architecture required to do that, enabling more precise prioritization of regions, product families, application segments, and competitive responses as the market moves through the rest of the decade.
For detailed analysis of this topic, please visit the official page: Construction Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti-Fog Coatings Market to Surpass $272.92M by 2032 at 3.5% CAGR
By PW Consulting, 2026-09-07
Anti-Fog Coatings Market 2026–2032: Strategic Intelligence for Capital Allocation and Product Roadmapping
The global anti-fog coatings market has entered a phase of structural maturation, where incremental volume growth is increasingly decided by formulation chemistry, substrate compatibility, regulatory shifts, and downstream OEM integration rather than broad-based demand expansion. For executives planning capital deployment, R&D prioritization, and regional sourcing strategies through the remainder of the decade, the difference between reactive positioning and proactive market leadership will hinge on how precisely they can read the interplay between hydrophilic performance requirements, sustainability mandates, and appliance-specific optical clarity thresholds. This introduction frames why a rigorously constructed market study is no longer a passive reference document but a decision-grade asset for 2026 strategy cycles.
Worldwide Respiratory Collector Market
From Volume Recovery to Value Discipline
Over the 2020–2025 historical window, the market demonstrated a clear trajectory of recovery and consolidation. Revenue climbed from approximately 163.15 million USD in 2020 to 215.0 million USD by 2025, reflecting not only post-pandemic normalization across optical, safety, and automotive supply chains but also the embedding of anti-fog functionality as a baseline expectation rather than a premium add-on. Moving into 2026, the forecast period signals a more measured pace of expansion. The overarching compound annual growth rate is tracked at 3.5 percent, with revenue projected to reach 217.29 million USD in 2026 and gradually advance toward 272.92 million USD by 2032. This growth profile is deliberately moderate, underscoring that top-line expansion will be earned through product endurance, regulatory alignment, and premiumized performance tiers rather than through aggressive volume plays alone.
Powder Tablet Press Mold Market
For strategists, the implication is clear. Budgeting and forecasting models that assume linear ramp-up will overstate short-term upside and underappreciate the segment-level divergence that defines the market. Some applications and substrates will see faster payback cycles because of embedded OEM validation and repeat procurement, while others will experience margin compression as formulation costs, compliance overhead, and processing complexity rise. A disciplined research baseline separates these trajectories, enabling leadership to allocate engineering resources, inventory positioning, and partnership investments where the probability-adjusted return is strongest.
Ceramic Watertight Concrete Market
What the Study Delivers Beyond Top-Line Estimates
A commercially useful market study must go past aggregate revenue and CAGR figures. It needs to translate market structure into operational levers that product managers, procurement leads, and corporate development teams can act upon. The full report is built around that operational logic. It maps how hydrophilic and permanent anti-fog chemistries are distributed across substrate families, where water-washable and abrasion-resistant systems create application-fit advantages, and which product types hold structural cost or performance advantages under specific manufacturing conditions. Rather than presenting segmentation as a static snapshot, the study connects each segment to real-world adoption drivers, process constraints, and switching costs that influence procurement behavior.
Equally important is the treatment of end-use demand. The analysis dissects how building and construction, automotive, aviation and aerospace, electronics, military and security, medical and safety industries, and ancillary sectors each approach fog control with different performance thresholds, certification burdens, and durability expectations. Readers gain a clarified view of where optical clarity, heat stability, UV resistance, and long-term hydrophilic retention matter most, and where cost-efficiency and ease of application dominate purchasing decisions. By layering substrate suitability, product chemistry, regional procurement patterns, and end-use specifications into a single analytical framework, the report equips teams to evaluate not only where demand is forming, but how it is likely to be served and monetized.
The study also incorporates competitive intelligence that is practical rather than ceremonial. It examines the positioning of leading participants such as FSI Coating Technologies, Momentive Performance Materials, Hydromer Inc., NSG Group, and WeeTect Material Limited, alongside recent market activity from firms including Cosmo Films, Solabs Nanotechnology GmbH, PPG Industries, Hanwha Chemical, and 3M. The intent is not to catalog announcements, but to interpret what they reveal about formulation priorities, OEM alignment, sustainability direction, and technology differentiation. Recent activity—such as updated premium coating highlights, transparent BOPET lidding film introductions for food packaging, the emergence of passive thermal anti-fog solutions, water-based eco-friendly formulations for automotive windshields, capacity expansion for waterborne coatings with green chemistry incentives, and the integration of embedded anti-microbial properties in next-generation AR headset coatings—collectively signals where the industry is pushing its technical frontier.
Why 2026 Decisions Require Segmented Precision
The strategic urgency of 2026 lies in the widening gap between broad market growth and segment-level opportunity. Companies that treat the market as a single demand pool risk misallocating resources to applications where regulatory friction, raw material cost structures, or processing complexity erode profitability. At the same time, firms that understand where glycerol esters remain the practical workhorse chemistry due to low raw material cost and established food-contact acceptability, and where proprietary in-house anti-fog technologies are being adopted to reduce supply chain expenses, can structure sourcing and formulation strategies with greater leverage.
This is particularly relevant for organizations navigating sustainability and compliance transitions. Demand for eco-friendly, water-based, and otherwise compliant coatings is reshaping both automotive windshield applications and high-end optical and automotive markets, supported in some regions by government incentives for green chemistry. At the same time, expert lens treatments and coatings can elevate production costs, making supply chain improvements and proprietary processing capabilities a meaningful source of margin protection. The market study provides the evidentiary backdrop required to decide when to invest in formulation upgrades, when to secure OEM-approved product lines, and when to prioritize geographic or substrate exposure that offers faster route-to-market clearance.
Competitive Structure and the Reality of Market Share
A frequently underestimated strategic input is market concentration. With CR3 at 24.6 percent and CR5 at 26.2 percent, the industry is fragmented enough to preserve innovation entry points and customer-specific formulation opportunities, yet consolidated enough that established players command meaningful technical credibility, certification track records, and OEM relationships. This structure matters for both incumbents and entrants. For incumbents, it rewards continued differentiation through permanent performance-based systems, abrasion resistance, optical clarity, and application-specific approvals. For challengers, it suggests that broad commodity positioning is unlikely to outperform targeted, performance-validated solutions in high-specification segments.
The profiled companies illustrate how differentiation is being built. One global leader emphasizes permanent performance-based, water-washable anti-fog coating systems and abrasion-resistant coatings across polyester film, plastics, glass, mirrors, and metal substrates, with product lines approved for demanding OEM environments. Another major supplier focuses on silicone-based anti-fog coatings that deliver long-term hydrophilic performance, high transparency, and optical clarity for automotive lighting, sensors, ADAS, safety glasses, visors, ophthalmics, and electric vehicle front-end modules. A third manufacturer builds its identity around premium hydrophilic anti-fog and condensation control coatings with heat- and UV-stable options for medical and safety devices, eyewear, sensors, LEDs, automotive windshields, and industrial substrates. A fourth provider contributes high-performance sol-gel hybrid anti-fogging coatings designed for automotive cameras, ADAS, surveillance cameras, optical filters, lenses, and plastic substrates. A fifth developer targets hydrophilic anti-fog coatings applied through spraying or dipping for plastic sheets, films, and injection-molded visors, with emphasis on permanent anti-fog and anti-scratch performance for helmet visors, face shields, goggles, mirrors, and freezer displays.
Read together, these profiles show that competitive advantage is not simply a matter of price, but of performance durability, substrate fit, application approval, and increasingly, environmental and safety compliance. Strategic planning should therefore evaluate partnerships, acquisitions, and internal development not only through the lens of market size, but through the lens of specification capture and OEM trust.
How to Use This Research in 2026 Planning Cycles
The study is designed to support multiple decision pathways at once. Product leaders can use the segmentation mapping to identify which substrate and product-type combinations warrant deeper formulation investment. Procurement and supply chain teams can use the demand patterns to anticipate where repeat buying, certification cycles, and durability requirements will pressure lead times and inventory planning. Corporate development teams can use the competitive and regulatory context to assess where green chemistry momentum, capacity expansion, and next-generation thermal or embedded-property coatings are likely to reshape supplier options. And executives overseeing regional exposure can use the geographic distribution of demand to weigh where concentration offers efficiency against where diversification reduces dependency risk.
Because the report is structured to preserve segment-level distinctions without flattening them into headline numbers, it allows leadership to conduct scenario planning with greater confidence. Teams can compare a strategy centered on automotive-adjacent optical performance against one emphasizing medical and safety device compatibility, and they can evaluate whether premium permanent coatings or more cost-efficient hydrophilic systems align better with their target customer base. The value of the research lies in making those trade-offs explicit rather than speculative.
What Remains in the Full Study
To preserve analytical integrity while still driving action, this introduction deliberately omits the detailed regional and application breakdowns, segment-specific revenue figures, and granular product-type proportions that constitute the core intelligence of the full report. Those figures are not ornamental. They are the decision scaffolding that enables precise market entry timing, budget sizing, and competitive positioning. Access to the complete dataset is necessary for teams that need to compare specific regional demand intensity, segment revenue shares, and end-use prioritization without relying on approximations.
The full study also expands the competitive landscape beyond the most visible leaders, providing a wider view of supplier positioning, application-specific strengths, and recent product and partnership activity that shapes near-term buyer behavior. For organizations preparing 2026 budgets, roadmap approvals, and regional sourcing reviews, that expanded view is where the difference between good strategy and implementable strategy is usually found.
Final Strategic Takeaway
The anti-fog coatings market is not defined by dramatic volatility, but by the cumulative effect of formulation performance, regulatory direction, OEM specification capture, and substrate-level manufacturing realities. With moderate overall growth and a fragmented-but-concentrated competitive structure, the winners in 2026 will be those who act on segment-level clarity rather than aggregate momentum. The full market study provides that clarity, pairing macro trajectory with operational segmentation, competitive interpretation, and recent industry signals that matter for product, procurement, and corporate strategy. For decision-makers who need to convert market visibility into concrete investment and partnership choices, the complete report is the necessary next step.
For detailed analysis of this topic, please visit the official page: Anti-Fog Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global zipper market is projected to grow steadily, with revenues increasing from 13,450 Million USD in 2020 to approximately 24,800 Million USD by 2035. This upward trajectory is fueled by urbanization, value-added product demand, and market expansion in emerging economies. Recent innovations in advanced zipper functionality and the integration of sustainable materials are accelerating growth further, positioning market leaders to capture greater value across multiple industries.
Read More - https://bussinessinsights.com/research-report/global-zipper
The global zipper market in 2025 is led by the apparel segment, which accounts for the largest share due to the widespread and diverse use of zippers in garment manufacturing. Luggage and bag applications follow, responding to growth in travel, outdoor activities, and fashion accessories. The footwear and automotive sectors also contribute significantly, driven by global lifestyle and design trends. Manufacturers are innovating to address durability, sustainability, and aesthetic demands across these key application verticals, ensuring robust market momentum.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-zipper
Frequently Asked Questions
Who are the key players in Global Zipper industry?
The top 5 players in the global zipper industry are YKK Group, SBS Zipper, RIRI Group, IDEAL Fastener, and Fujian SBS Zipper Science & Technology. These companies are leaders in innovation, manufacturing, and global distribution, catering to major apparel, luggage, and footwear brands worldwide.
What is the Global Zipper growth?
The global zipper market has experienced steady growth, driven by the fashion and luggage sectors. For instance, YKK Group reported increased sales in 2023 due to heightened demand in the apparel industry, especially in Asia-Pacific, reflecting a positive trend in the overall zipper market.
Which segment accounted for the largest Global Zipper share?
The apparel segment accounts for the largest market share of global zippers, owing to their extensive use in jackets, trousers, jeans, and fashion accessories. Leading fashion brands’ increasing requirement for quality closures fuels this segment’s growth and dominance in the zipper industry.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Market revenue for herbal cosmetics has shown consistent growth from 2020, with a sharp uptick post-2023 tied to evolving consumer lifestyles and increased adoption of herbal beauty solutions worldwide. Revenue is projected to escalate from USD 14,200 Million in 2025 to approximately USD 31,800 Million by 2035, highlighting the exponential potential within emerging markets and digital retail platforms. This impressive trajectory is supported by rising incomes, ongoing innovation, and expansion of product lines addressing holistic wellness, ensuring a robust and expanding market outlook for the forecast period.
Read More - https://bussinessinsights.com/research-report/global-herbal-cosmetics
The application landscape of herbal cosmetics in 2025 is led by personal care products, making up the largest share. Anti-aging solutions and hair treatment applications closely follow, reflecting rising demand for targeted, natural remedies addressing specific consumer concerns like skin rejuvenation and damage repair. The growth in beauty clinics utilizing herbal products further bolsters market expansion. Brands such as VLCC and Forest Essentials focus on tailoring their portfolios to match these dominant application areas. This segmentation highlights a consumer shift towards specialized herbal solutions for everyday care, as well as professional and functional uses within wellness and aesthetic treatments.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-herbal-cosmetics
Frequently Asked Questions
Who are the key players in Global Herbal Cosmetics industry?
The top five players in the Global Herbal Cosmetics industry are Himalaya Herbals, Dabur India Ltd., Weleda AG, Estee Lauder Companies Inc., and Bio Veda Action Research Co. These companies are recognized for their extensive product portfolios, innovation in herbal formulations, wide distribution networks, and strong global presence in natural skincare and beauty products.
What is the Global Herbal Cosmetics growth?
The Global Herbal Cosmetics market has witnessed robust growth, with a CAGR of over 7% in recent years. This growth has been fueled by increasing consumer preference for natural products. For example, Himalaya Herbals reported a significant sales increase in 2023, driven by expanding markets in Asia and Europe.
Which segment accounted for the largest Global Herbal Cosmetics share?
The skincare segment holds the largest share in the Global Herbal Cosmetics market, accounting for over 35%. Skincare products such as creams, lotions, and cleansers are preferred due to rising awareness about the benefits of herbal and chemical-free ingredients, catering to consumer demands for natural and safe alternatives.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Piperylene Market to Hit $1,231M by 2032, 6.9% CAGR from $780M in 2025
By PW Consulting, 2026-09-07
Piperylene Market Outlook 2026 Strategic Intelligence for Chemical Industry Leaders
The global piperylene market stands at a pivotal inflection point as we move through 2026. For executives, procurement strategists, and long-range planners operating across the chemical value chain, understanding where this market is heading is no longer a matter of speculative forecasting. It is a direct requirement for capital allocation, supply chain resilience, and competitive positioning. Our newly released Piperylene Market research study provides a rigorous, data-grounded examination of the structural forces shaping the sector over the next seven years. The report is engineered to translate macro-level trajectory shifts into actionable commercial intelligence, enabling leadership teams to calibrate pricing negotiations, capacity commissioning decisions, and strategic partnerships with precision.
Cognition-Enhancing Drugs Market
Market Trajectory and the 2026 Decision Horizon
The piperylene sector has demonstrated consistent expansion over the past half-decade, driven by recovering downstream manufacturing activity, sustained demand from polymer and resin applications, and supply chain recalibration following recent logistical disruptions. Historical data from 2020 through 2025 reveals a market that has systematically climbed from approximately 598.5 million USD to 780.0 million USD, reflecting compound annual growth that underscores the building block role piperylene plays across industrial chemistry portfolios. As we enter the forecast window spanning 2026 through 2032, the trajectory points toward sustained expansion, with the overall market size projected to reach roughly 812.11 million USD in the immediate 2026 horizon and continuing upward toward 1.23 billion USD by 2032.
Worldwide Marine Annunciator Panels Market
The compound annual growth rate across the forecast period is estimated at 6.9 percent, a figure that should be interpreted not as a simple growth headline but as a structural signal. A rate at this level indicates that demand pull from end-use industries is out-pacing the incremental capacity additions from C5 fractionation and steam-cracking streams, while simultaneously highlighting the importance of feedstock reliability and regional supply balancing. For corporate planners, this growth cadence carries several immediate implications. Budget cycles for 2026 and 2027 must account for pricing volatility that accompanies steady demand expansion, particularly as fewer new entrants can rapidly scale to capture margin share. Procurement teams should begin modeling scenario-based supply contracts that reflect tightening availability in high-purity segments, while capacity expansion teams need to weigh the timing of specialty-grade investments against the risk of premium compression if competing producers bring additional fractionation capacity online in synchronized windows. The forecast period is constructed precisely to give leadership teams the visibility required to make these timing decisions with confidence rather than reactive guesswork.
Worldwide Airport Scrubber Dryers Market
Segment Architecture and Commercial Leverage Points
A market of this scale and growth complexity cannot be navigated with aggregate figures alone. The strategic value of any forecasting exercise lies in its ability to reveal how value is distributed across product specifications, application verticals, and geographic supply nodes. This study segments the piperylene market across multiple operational dimensions, providing a layered view of where margin concentration, demand intensity, and supply bottlenecks are forming.
Product Grade Dynamics
The market structure reflects a clear dominance of high-purity piperylene, which accounts for the substantial majority of reported revenue, with technical-grade material representing a smaller but commercially meaningful residual share. For downstream users, the divergence between these grades is not merely a purity specification. It translates directly into processing flexibility, resin performance characteristics, and suitability for high-value elastomer and adhesive formulations. High-purity streams command pricing premiums and require tighter fractionation control, while technical-grade material is frequently directed toward less performance-sensitive applications where cost optimization is prioritized. Understanding the relative growth velocity of each grade, and how supply availability shifts as cracking yields and separation technologies evolve, enables procurement and R&D teams to align material specifications with total cost of ownership rather than sticker price alone. Our report isolates the drivers behind grade-level demand shifts and maps the implications for sourcing strategies across both high-purity and technical-grade categories.
Application-Level Demand Architecture
Piperylene demand is distributed across several core industrial applications, each with distinct consumption profiles, price sensitivity, and growth catalysts. The largest application segment centers on resins, where piperylene serves as a foundational building block for hydrocarbon resins used in adhesives, coatings, and rubber compounding formulations. This segment carries substantial volume and is particularly sensitive to automotive, packaging, and construction sector activity. The rubber segment represents a second major consumption pillar, with piperylene incorporated into synthetic rubber streams and specialty elastomer formulations that support tire manufacturing, industrial hose production, and vibration-damping components. Adhesives and coatings form additional downstream demand nodes, each with their own regulatory, performance, and reformulation trajectories.
Because these application verticals do not expand uniformly, aggregate market growth can obscure meaningful divergence beneath the surface. A resin-focused producer may experience materially different demand signals than a coatings supplier, even within the same calendar year. The report dissects these application-level consumption patterns to help clients identify where demand is structurally expanding, where substitution risk is rising, and where downstream innovation is likely to alter piperylene uptake over the 2026 to 2032 window. By mapping revenue concentration by application without exposing the underlying granular percentages, the study preserves the directional intelligence leadership teams need while maintaining competitive confidentiality and prompting deeper consultation for precise allocation planning.
Regional Supply and Demand Architecture
Geographic segmentation is equally critical for strategic planning. Piperylene supply is inherently tied to steam-cracking and C5 fractionation networks, meaning regional capacity geography shapes both pricing dynamics and logistics costs. The market shows pronounced activity across major industrial regions, with Asia Pacific reflecting the largest aggregate market size, North America and Europe maintaining substantial mature demand bases, and Latin America and the Middle East and Africa representing growing but comparatively smaller consumption nodes.
Regional analysis in this study is structured to reveal where supply tightness may emerge, where import dependency is likely to increase, and where localized fractionation capacity could reshape trade flows. For multinational chemical groups, this geographic lens is indispensable for evaluating sourcing diversification, evaluating freight and inventory exposure, and anticipating regulatory or tariff shifts that could alter regional cost baselines. The report maps these regional dynamics to support decisions around distribution hub placement, contract structuring with domestic versus imported sources, and long-term capacity partnerships in high-growth corridors.
Competitive Landscape and Strategic Positioning
The piperylene market is characterized by a concentrated supplier base, with the top three firms accounting for approximately 68.5 percent of market share and the top five firms reaching roughly 85.2 percent. This level of concentration signals an industry where scale, integration, and feedstock reliability create durable competitive advantages. It also means that pricing frameworks, availability windows, and long-term contract terms are heavily influenced by the strategic behavior of a relatively small number of major producers.
Our research profiles a comprehensive set of key industry participants, offering detailed assessments of each company's operational footprint, feedstock positioning, and downstream market orientation.
LyondellBasell Industries N.V., headquartered in Rotterdam, operates as a global producer of piperylene as a key olefinic building block extracted from steam-cracked C5 fractions, with integrated manufacturing and supply to downstream chemical and rubber industries. ExxonMobil Chemical, based in Irving, Texas, stands as a major producer and supplier of piperylene through its petrochemical operations, with a focus on high-purity olefins for industrial applications. Chevron Phillips Chemical Company LLC, located in The Woodlands, Texas, is an active manufacturer of piperylene derived from C5 fractions, serving olefins and aromatics markets globally. Zeon Corporation, based in Tokyo, is a specialized producer extracting piperylene from C5 fractions for use in petroleum resins, synthetic rubbers, and specialty chemicals. LOTTE Chemical Corporation, headquartered in Seoul, functions as a key supplier of piperylene as a C5 by-product for industrial chemical synthesis and elastomers. Eastman Chemical Company, with operations in Kingsport, Tennessee, produces piperylene within its olefin and aromatics portfolio for downstream applications in resins and coatings.
Shell Chemicals, headquartered in The Hague, provides an integrated supply of piperylene from steam cracking operations for global chemical markets. Sinopec, based in Beijing, is a major Chinese petrochemical producer of piperylene from C5 fractions with extensive export capabilities. Formosa Chemicals & Fibre Corporation, operating out of Taipei, is an active manufacturer of piperylene for the industrial chemical sector. Mitsui Chemicals, Inc., headquartered in Tokyo, supplies and produces piperylene as part of its C5 chemical offerings.
The competitive analysis in this study extends beyond company profiles to evaluate strategic behavior, capacity positioning, integration advantages, and likely responses to market expansion. For clients evaluating partnership opportunities, supplier diversification, or competitive benchmarking, these profiles provide an essential reference point for understanding which producers are best positioned to supply high-purity streams, which firms are expanding export reach, and where supply concentration may translate into negotiating leverage.
Regulatory and Structural Dynamics Shaping the Market Environment
The piperylene market does not operate in isolation from broader regulatory and policy shifts affecting industrial chemicals and downstream manufacturing standards. While many regulatory developments directly target pharmaceutical or biologic pathways, the broader signal they send regarding review timelines, evidence requirements, and accelerated approval frameworks influences how industrial supply chains evaluate compliance posture, quality assurance, and change-management risk. Recent policy updates from U.S. regulatory bodies highlight a broader administrative emphasis on streamlined decision-making and efficiency in approval processes, including the establishment of new default standards that require a single robust pivotal study plus confirmatory evidence to reduce review timelines, as well as the implementation of accelerated approval pathway updates and real-time trial capabilities to enhance efficiency in development reviews.
For chemical market participants, the relevance of these developments lies less in direct pharmaceutical overlap and more in the structural direction they reveal. An environment oriented toward faster review cycles, clarified evidentiary expectations, and reduced procedural lag tends to indirectly favor sectors that can demonstrate consistent quality, traceable sourcing, and reliable product performance. Companies that maintain rigorous specification control, robust documentation, and predictable supply continuity are better positioned to adapt to evolving downstream expectations across multiple regulated end-use sectors. The report incorporates these structural dynamics to help clients assess how administrative and compliance momentum may influence purchasing criteria, supplier qualification processes, and entry requirements in sensitive downstream markets.
Why This Research Matters for 2026 Decision-Making
The 2026 to 2032 forecast period is not merely a statistical exercise. It is the operational window in which capacity commitments, long-term supply contracts, geographic sourcing strategies, and application development roadmaps will be locked in. A market growing at the projected pace with concentrated supplier control and divergent application-level demand creates a decision environment where generalized market awareness is insufficient. Leadership teams need segmented visibility into where value is accruing, which grade and application combinations are expanding fastest, how regional supply balances are shifting, and which competitive players are most likely to influence availability and pricing over the next several years.
This Piperylene Market study is designed to provide exactly that layered intelligence. It synthesizes historical trajectory, forecast growth, segmentation architecture, competitive positioning, and structural market dynamics into a single coherent framework. The result is a decision-support tool that can be applied across procurement, operations, corporate development, and market strategy functions. By presenting the macro contours and segmentation logic in depth while reserving the full granularity of regional and application-level figures for the complete report, the study establishes analytical credibility and signals the richness of the underlying data without prematurely disclosing the operational detail that would otherwise reduce the incentive to engage with the full intelligence package.
What the Report Delivers
The complete market research package is structured to support a wide range of internal strategic processes. Clients receive detailed segmentation analysis that breaks down market size and growth by product grade, application, and region over both historical and forecast windows. The study includes competitive profiling of major producers and an assessment of concentration dynamics that shape pricing influence and supply reliability. It also provides contextual analysis of the regulatory and structural developments that influence downstream procurement expectations and industry-wide compliance posture.
In addition to core sizing and segmentation, the report examines demand catalysts by application vertical, maps the implications of regional supply geography for sourcing and logistics, and evaluates competitive positioning across integrated producers and specialized fractionators. Methodology transparency is maintained throughout, allowing clients to understand the assumptions, data treatment, and forecast framework underpinning the projections. This combination of macro trajectory, segmentation intelligence, competitive context, and structural analysis is intended to serve as a foundational reference for 2026 planning cycles and multi-year capital and commercial strategy development.
Strategic Takeaway for Leadership Teams
The piperylene market is expanding along a steadily upward path, shaped by concentrated supply, application-specific demand growth, and regional supply geography that will increasingly influence cost and availability. For organizations operating in or adjacent to this market, the strategic imperative is clear: aggregate awareness is no longer enough. The decisions that will determine competitive advantage in 2026 and beyond depend on a more granular understanding of grade-level dynamics, application-level demand divergence, regional supply positioning, and the strategic behavior of the dominant producers that shape market conditions.
This Piperylene Market research report is built to provide that understanding in a format calibrated for executive use. It offers the analytical depth required to build trust in the forecast framework while preserving the full operational detail for the complete release. For teams preparing sourcing strategies, capacity evaluations, competitive benchmarking, and multi-year growth planning, the report provides a structured foundation for informed, forward-looking decision-making in a market where timing, specification alignment, and supply reliability will increasingly determine commercial outcomes.
For detailed analysis of this topic, please visit the official page: Piperylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Make-Up Products Packaging Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The global make-up products packaging market is projected to grow from $8,300 million in 2020 to $14,700 million by 2035, reflecting robust expansion driven by sustainability trends, premiumization, and the growth of the online cosmetics sector. The market has experienced a consistent upward trajectory, with notable acceleration post-pandemic as beauty consumption rebounds. Revenue growth highlights the importance of ongoing innovation in packaging design, supply chain resilience, and repositioning strategies to cater to evolving consumer expectations and regulatory requirements worldwide.
Read More - https://bussinessinsights.com/research-report/global-make-up-products-packaging
Foundation leads the applications market in 2025 with 28% share, attributable to its widespread use and frequent repurchases globally. Lip products secure 22% share, reflecting ongoing innovation and strong consumer demand for varied formats. Eye make-up accounts for 19%, while nail polish and skincare register 13% and 12% respectively, driven by growing at-home beauty routines. Other applications comprise the remaining 6%. The application breakdown underscores the steady growth in multi-function cosmetic formulations, with packaging solutions increasingly tailored for specific end-uses, thus driving the need for versatility in design and materials.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-make-up-products-packaging
Frequently Asked Questions
Who are the key players in Global Make-Up Products Packaging industry?
The key players include Albéa Group, HCP Packaging, Amcor plc, AptarGroup Inc., and Lumson S.p.A. These companies lead the industry with innovative packaging solutions, global presence, sustainability initiatives, and strong partnerships with top cosmetic brands, offering a diverse range of products such as compacts, tubes, jars, and pumps.
What is the Global Make-Up Products Packaging growth?
The Global Make-Up Products Packaging market has seen notable growth, driven by rising cosmetic consumption and sustainable packaging demand. For instance, in 2023, AptarGroup announced increased investments in eco-friendly materials and rapid expansion in Asia-Pacific, contributing to robust market growth in that region.
Which segment accounted for the largest Global Make-Up Products Packaging share?
Face make-up application (including foundations and powders) holds the largest market share in global make-up products packaging. The segment benefits from consistent consumer demand and frequent launches, pushing companies like HCP Packaging to innovate with airless containers and advanced, user-friendly compacts.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Electric Motor for Household Appliances Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The global revenue for electric motors used in household appliances is projected to rise from $24,350 million in 2020 to $48,790 million by 2035. This uninterrupted growth trajectory is fueled by rising adoption of energy-efficient appliances, technological advancements in motors, and aggressive market expansion in Asia-Pacific. The steepest revenue jumps align with key product launches and technology upgrades around 2025 and 2030, positioning the segment as a critical driver for the home appliances industry.
Read More - https://bussinessinsights.com/research-report/global-electric-motor-for-household-appliances
Refrigerators and washing machines remain the top applications for electric motors in household appliances, securing a combined market share of over 50% in 2025. As energy efficiency and reliability are crucial in continuous-use appliances, robust motors are prioritized by manufacturers. Air conditioners are the next significant segment, driven by rising urbanization and climate change adaptation. Vacuum cleaners and dishwashers are witnessing incremental demand, while the 'others' category covers incremental innovations in emerging smart home gadgets. The shifts in application share reflect both core needs and evolving consumer lifestyles.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-electric-motor-for-household-appliances
Frequently Asked Questions
Who are the key players in Global Electric Motor for Household Appliances industry?
The top five players in the global electric motor for household appliances market are Nidec Corporation, Johnson Electric, Siemens AG, ABB Ltd., and WEG S.A. These companies offer advanced and energy-efficient motors, holding significant global market shares, and consistently invest in innovation and expanding their product portfolios.
What is the Global Electric Motor for Household Appliances growth?
The Global Electric Motor for Household Appliances market has witnessed notable growth, driven by rapid adoption of energy-efficient appliances. For instance, Johnson Electric reported a surge in demand for compact, high-efficiency motors in 2023 due to increasing governmental regulations and rising consumer awareness about energy savings.
Which segment accounted for the largest Global Electric Motor for Household Appliances share?
The washing machine application segment accounted for the largest share in the market. This is attributed to rising urbanization, increasing disposable incomes, and the continual launch of technologically advanced and energy-efficient washing machines, which require high-performance electric motors to deliver efficient operation.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Moisture Analyzer Market Hits $159M in 2025, Projected 6.5% CAGR Through 2032
By PW Consulting, 2026-09-07
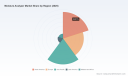
Strategic Intelligence for the Moisture Analyzer Market: Navigating Growth and Compliance in 2026
The moisture analyzer market stands at a critical inflection point as enterprises across food, pharmaceutical, and industrial sectors confront tightening quality standards and evolving regulatory landscapes. For decision-makers operating in 2026, understanding the trajectory of this specialized instrumentation sector is no longer optional. It is a strategic imperative that shapes procurement planning, compliance readiness, and competitive positioning. Our latest market research delivers a comprehensive analytical framework designed to translate complex market signals into actionable intelligence, enabling organizations to allocate capital with confidence and anticipate shifts before they become industry-wide realities.
Worldwide Water-based Fire Retardant Coating Market
This analysis draws upon a rigorously constructed dataset spanning historical performance from 2020 through 2025, with forward-looking projections extending to 2032. The base year of 2025 establishes a reliable foundation for evaluating growth trajectories, while the forecast period captures the nuanced dynamics that will define procurement strategies, product development roadmaps, and regional expansion plans over the next several years. What follows is an executive preview of the strategic value embedded within this research, structured to equip senior leaders with the contextual awareness necessary for high-stakes decision-making.
Worldwide Electrical Resistance Alloy Market
Market Trajectory and Growth Architecture
The moisture analyzer market has demonstrated consistent expansion over the past half-decade, reflecting the instrument category's integral role in quality control workflows. Historical revenue data reveals a market that has steadily climbed from approximately 120.0 million USD in 2020 to an estimated 159.0 million USD by 2025. This progression underscores the sustained demand for precise moisture measurement solutions across laboratory, process, and field environments. The upward momentum is projected to continue through the forecast horizon, with revenue expected to reach 171.94 million USD in 2026 and subsequently advance toward 240.0 million USD by 2032.
Seated Abdominal Curl Machine Market
The compound annual growth rate of 6.5 percent across the 2026 to 2032 forecast period signals a market characterized by steady, sustainable expansion rather than speculative volatility. For enterprises evaluating capital expenditure allocations, this growth profile offers a predictable backdrop against which to assess supplier relationships, inventory strategies, and technology refresh cycles. The projected revenue milestones across the forecast years—including 176.97 million USD in 2027, 196.41 million USD in 2028, 209.67 million USD in 2029, 213.96 million USD in 2030, and 229.52 million USD in 2031—illustrate a maturation path that rewards organizations capable of aligning their procurement and operational strategies with long-term market rhythms.
Understanding these aggregate figures is only the starting point. The strategic value of our research lies in its ability to contextualize macro-level growth within the operational realities of specific procurement scenarios, compliance requirements, and competitive pressures that vary significantly across end-use sectors and geographic territories. We deliberately refrain from presenting granular regional or application-level breakdowns in this preview, as those nuanced allocations require the full analytical framework to interpret correctly and apply effectively within your organization's unique operational context.
Structural Dynamics Shaping Procurement and Compliance
The moisture analyzer market does not operate in a vacuum. It is shaped by an intricate web of regulatory mandates, quality infrastructure initiatives, and standardization requirements that directly influence product specifications, validation protocols, and total cost of ownership calculations. In 2026, organizations navigating this landscape must contend with a regulatory environment that demands rigorous alignment with recognized testing methodologies and documentation standards.
In the United States, halogen lamp moisture analyzers must support validation against established moisture determination guidelines, with documentation frameworks that satisfy FDA and GMP requirements. This compliance layer extends beyond simple equipment selection; it encompasses internal standard operating procedure validation, repeatability protocols, and audit trail maintenance that align with ISO quality management standards. Organizations that treat compliance as an afterthought risk operational disruptions, whereas those that embed regulatory alignment into their procurement criteria gain a structural advantage in audit readiness and quality assurance continuity.
Food processing and pharmaceutical applications face additional layers of scrutiny. Products deployed in these sectors must align with FDA and FSSAI standards, reflecting the global nature of modern supply chains. Simultaneously, domestic manufacturing initiatives such as Make in India and China's Quality Infrastructure Development Plan are reshaping regional supply dynamics, encouraging localized production and creating new procurement pathways for organizations seeking to diversify their supplier base or reduce dependency on single-source channels.
The agricultural sector presents its own calibration complexities. Official moisture meters designated for inspected grains and commodities undergo regular calibration updates, with May 2026 marking a significant refresh cycle. Organizations operating in grain grading, commodity inspection, or agricultural quality control must ensure that their instrumentation aligns with the latest calibration standards to maintain official inspection credentials and avoid compliance gaps that could disrupt trading operations or quality certifications.
Pricing structures further complicate procurement decisions. New moisture analyzers generally range from 1,500 to 10,000 USD depending on configuration, capabilities, and intended application environment. Used units offer a cost-effective alternative, with prices spanning 500 to 5,000 USD based on brand reputation, equipment condition, and functional specifications. Evaluating these options requires more than a simple price comparison. It demands an understanding of lifecycle costs, calibration maintenance requirements, warranty coverage, and the specific performance thresholds demanded by your operational workflows.
Competitive Landscape and Strategic Positioning
The moisture analyzer market features a diverse array of established manufacturers and specialized instrument providers, each competing on dimensions of precision, compliance readiness, application specificity, and integration capabilities. Market concentration data indicates that the top three players command approximately 35.5 percent of total market revenue, while the top five collectively hold around 45.0 percent. This concentration profile suggests a market that remains accessible to mid-tier and niche suppliers while still dominated by organizations with substantial R&D investment capacity and global distribution networks.
Sartorius AG, headquartered in Göttingen, Germany, has built a strong reputation around its MA series halogen and infrared moisture analyzers designed for laboratory and process quality control environments. Their product portfolio reflects a focus on precision measurement workflows where repeatability and documentation integrity are paramount. Mettler-Toledo International Inc., based in Columbus, Ohio, USA, offers the HX204 and MA160 halogen and infrared moisture analyzers, with particular emphasis on ASTM and FDA compliance. Their recent selection for a US Food and Drug Administration solicitation in April 2026 underscores the competitive advantage that regulatory alignment can provide, signaling to procurement teams that compliance-certified instrumentation is increasingly a differentiator in public and regulated sector procurement.
Kett Electric Laboratory Co., Ltd., operating from Tokyo, Japan, has carved a specialized position in grain and seed moisture testing for agriculture and food industries, complemented by a significant R&D investment announced in October 2024 aimed at enhancing accuracy and efficiency. Perten Instruments, headquartered in Hällsta, Sweden, provides the AM 5200 and MA series grain moisture meters that carry official inspection approval, aligning directly with the calibration and standardization requirements emphasized by agricultural regulatory bodies. A&D Company, Ltd., also based in Tokyo, delivers high-precision moisture analyzers tailored for pharmaceutical, food, and chemical applications, reflecting a cross-sector versatility that appeals to organizations with diverse quality control needs.
Shimadzu Corporation, from Kyoto, Japan, contributes UniBloc and infrared moisture analyzers optimized for laboratory quality control workflows. Thermo Fisher Scientific Inc., based in Waltham, Massachusetts, USA, extends the competitive field into process integration with inline and benchtop moisture analyzers designed for seamless connection with process automation systems. Ohaus Corporation, operating from Parsippany, New Jersey, USA, offers the MB series digital moisture analyzers serving food, pharmaceutical, and industrial applications, with the MB120 model launched in April 2024 targeting these sectors specifically. CEM Corporation, from Matthews, North Carolina, USA, launched a novel Quartz Halogen Moisture Analyzer in June 2024, positioning it as a rapidly drying infrared solution for pharmaceuticals, plastics, dairy powders, and processed foods.
PCE Instruments, headquartered in Meschede, Germany, provides halogen and digital moisture analyzers for general industrial and agricultural applications, while Michell Instruments Inc., based in Greenville, South Carolina, USA, specializes in trace moisture analyzers for process and industrial gas analysis. Alliance Scale rounded out recent product activity with a March 2024 launch of a moisture analyzer offering single-step quality control for grains, foods, fish, meat, nuts, and seafood using halogen heating elements. This diverse competitive field means that procurement decisions cannot be reduced to brand recognition alone. Organizations must evaluate how each supplier's product architecture aligns with their specific application requirements, compliance mandates, integration preferences, and total cost of ownership parameters.
Product Innovation and Market Evolution
Recent product launches and R&D investments reveal a market that is actively responding to demand for faster measurement cycles, broader application coverage, and tighter integration with existing quality management systems. The introduction of halogen-based solutions targeting single-step quality control across diverse food matrices reflects a trend toward workflow simplification without sacrificing measurement precision. Similarly, novel quartz halogen configurations designed for rapid drying in pharmaceutical and dairy powder applications indicate that speed and throughput are becoming increasingly competitive differentiators alongside traditional accuracy metrics.
Investment in R&D to enhance accuracy and efficiency, as demonstrated by recent commitments from key market participants, suggests that the technological frontier for moisture analysis is still advancing. Organizations evaluating equipment refresh cycles or new facility deployments should consider not only current performance specifications but also the innovation trajectory of their preferred suppliers. A supplier with a demonstrated commitment to R&D investment is better positioned to deliver firmware updates, calibration refinements, and application-specific enhancements over the equipment lifecycle, reducing the risk of technological obsolescence.
Process integration represents another frontier of evolution. Inline moisture analyzers that communicate seamlessly with process automation systems enable real-time quality adjustments, reducing waste, minimizing off-spec production, and enhancing overall operational efficiency. As manufacturing environments increasingly adopt data-driven quality control paradigms, the ability of moisture analysis instruments to feed actionable data into broader process control architectures becomes a strategic consideration rather than a mere technical specification.
Strategic Implications for 2026 Decision-Makers
Translating market intelligence into operational strategy requires a structured approach that accounts for the interplay between growth trajectories, regulatory requirements, competitive dynamics, and internal operational priorities. For organizations making procurement, capital allocation, or market expansion decisions in 2026, several strategic themes emerge from the broader market landscape.
First, compliance readiness must be elevated from a procurement checkpoint to a strategic procurement criterion. Equipment that satisfies ASTM guidelines, FDA and GMP documentation requirements, and ISO-aligned validation protocols reduces the administrative burden of audit preparation and minimizes the risk of compliance-related disruptions. In regulated sectors such as pharmaceuticals and food processing, this alignment directly impacts continuity of operations and market access.
Second, total cost of ownership calculations should extend beyond initial purchase price to encompass calibration maintenance, validation documentation, firmware support, and potential integration costs with existing quality management or process automation systems. The availability of used equipment in the 500 to 5,000 USD range offers budget flexibility, but organizations must weigh those savings against potential limitations in warranty coverage, calibration traceability, and supplier support responsiveness.
Third, supplier diversification and regional supply chain considerations merit careful evaluation. Domestic manufacturing initiatives and evolving quality infrastructure programs are creating new procurement pathways that may reduce lead times, improve local support responsiveness, and align with organizational sustainability or supply chain resilience objectives. Understanding the regional availability of specific product configurations and the compliance credentials of local suppliers can inform more resilient procurement strategies.
Fourth, the competitive concentration profile of the market suggests that while dominant suppliers offer established reliability and broad application coverage, there remains meaningful opportunity to engage with specialized providers whose product architectures are optimized for specific application matrices or regulatory environments. Procurement teams that evaluate both broad-line and specialized suppliers are better positioned to identify solutions that balance performance, compliance, and cost-effectiveness for their unique operational context.
What the Full Research Delivers
The preview presented here captures the strategic contours of the moisture analyzer market but does not substitute for the depth of analysis required to inform specific procurement decisions, competitive benchmarking exercises, or market entry evaluations. Our comprehensive research report provides the structured analytical framework necessary to translate macro-level market signals into organization-specific intelligence.
The full report delivers detailed segmentation analysis across product type, application sector, and geographic territory, enabling readers to identify the specific growth pockets and procurement dynamics most relevant to their operational footprint. It includes in-depth competitive profiling that extends beyond product summaries to examine market positioning, recent strategic developments, and the implications of regulatory milestones for supplier evaluation. The report also provides scenario-based forecasting that helps organizations model the impact of different procurement strategies, technology refresh cycles, and compliance investment priorities across the forecast horizon.
Additional analytical modules cover the calibration and standardization landscape, including the implications of official moisture calibration updates and the documentation requirements associated with regulated sector procurement. Pricing analysis extends beyond aggregate ranges to examine how configuration complexity, application specificity, and compliance certification levels influence equipment costs across different procurement scenarios. The report also integrates regulatory tracking that maps upcoming compliance milestones, standardization updates, and quality infrastructure initiatives to specific procurement timelines and operational planning cycles.
For organizations seeking to benchmark their current instrumentation portfolio against market standards, evaluate alternative supplier relationships, or assess the strategic implications of market growth for capital planning, the full research report provides the granular, structured intelligence necessary to move from awareness to action. The complete segmentation breakdowns, competitive development timelines, regulatory compliance mapping, and scenario-based forecasting tools are available through our full report access portal.
Conclusion
The moisture analyzer market in 2026 presents a landscape defined by steady growth, increasing regulatory complexity, and accelerating product innovation. Organizations that approach procurement and strategic planning with a clear understanding of these dynamics are better positioned to optimize capital allocation, ensure compliance readiness, and maintain competitive advantage in quality-critical operations. This research preview has outlined the strategic framework necessary to interpret market signals and align decision-making with long-term growth trajectories.
The complete market research report provides the detailed segmentation intelligence, competitive analysis, regulatory mapping, and scenario-based forecasting required to translate this strategic awareness into precise, organization-specific action. We invite senior leaders, procurement directors, and quality assurance executives to access the full report for a comprehensive evaluation of the moisture analyzer market's structure, dynamics, and opportunities across the 2026 to 2032 forecast period.
For detailed analysis of this topic, please visit the official page: Moisture Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com